Managing Money in Retirement
A Practical Guide
Updated: September 2026
Written by: Golden Living Today Editorial Team
Sources reviewed: September 2026
Retirement should offer opportunities to enjoy life—not constant worry about whether your money will last. Whether you are already retired or preparing for the future, understanding your income, spending, savings, debt, taxes, insurance, and healthcare costs can help you make more informed decisions.
A retirement plan does not need to be complicated. It should, however, reflect your actual circumstances, priorities, and resources. Reviewing it regularly can help you adjust when expenses, benefits, health needs, or family responsibilities change.
💰 Financial Disclaimer: The information provided in this article is for general educational and informational purposes only and should not be considered financial, investment, tax, legal, insurance, or retirement-planning advice. Individual circumstances vary. Consider consulting an appropriately qualified professional before making significant financial decisions.
In This Article
• Create a Realistic Retirement Budget
• Plan for Taxes and Retirement Withdrawals
• Protect Yourself From Financial Scams
• Review Your Insurance and Medicare Coverage
• Prepare for Healthcare and Long-Term Care Costs
• Keep Beneficiaries and Important Documents Current
• Know When to Seek Professional Help
Know Your Retirement Income
Begin by identifying every source of money you expect to receive. Common retirement-income sources may include:
• Social Security benefits
• Pension or annuity payments
• Withdrawals from 401(k), 403(b), or similar workplace plans
• Traditional or Roth IRA withdrawals
• Part-time or self-employment income
• Dividends, interest, or other investment income
• Rental income
• Veterans benefits
• Other government or employer benefits
Separate dependable monthly income from income that may change. Social Security and some pensions may arrive regularly, while investment returns, retirement-account withdrawals, rental income, and part-time earnings can fluctuate.
Use the amount that is actually available for spending—not simply the gross benefit amount. Medicare premiums, taxes, insurance premiums, and other deductions may be taken from a payment before it reaches your bank account. For example, Medicare Part B premiums and voluntary federal tax withholding may be deducted from Social Security payments.
Create a list containing:
• The name of each income source
• The amount received
• How often it is received
• Whether taxes are withheld
• Whether the amount is fixed or may change
• Whether it will continue after the death of a spouse
Review Social Security, pension, and retirement-plan statements periodically for accuracy. The Department of Labor recommends comparing expected retirement income with likely expenses and reviewing retirement accounts regularly.
Create a Realistic Retirement Budget
A useful budget reflects how you actually spend money—not how you think you should spend it.
Start with regular monthly expenses:
• Mortgage or rent
• Property taxes
• Utilities
• Groceries and household supplies
• Transportation
• Insurance
• Healthcare
• Debt payments
• Telephone and internet service
• Personal care
• Entertainment and hobbies
• Charitable giving
Next, include expenses that do not occur every month:
• Home maintenance and repairs
• Vehicle registration and repairs
• Insurance premiums paid annually
• Holiday and birthday expenses
• Travel
• Pet care
• Dental work
• Eyeglasses or hearing aids
• Tax-preparation costs
• Family assistance
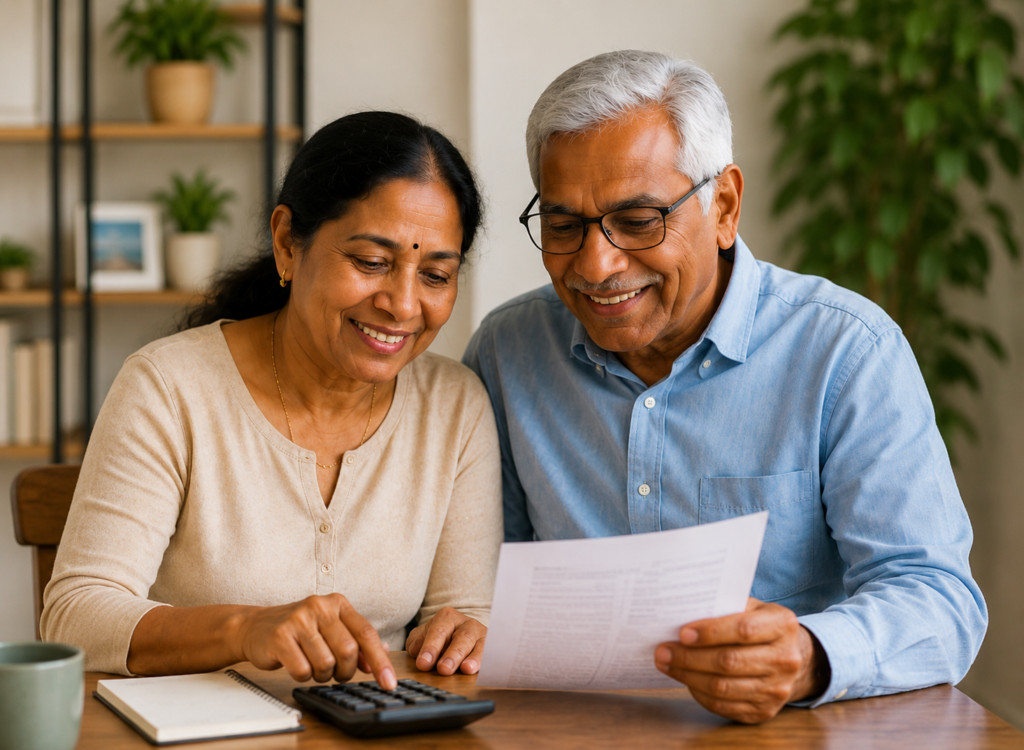
Divide estimated annual expenses by 12 and set aside part of the cost each month. For example, if you expect to spend $1,200 a year on home and vehicle repairs, setting aside $100 monthly may make those expenses easier to manage.
Remember that some expenses may change during retirement. Work-related costs may decline, while healthcare, home maintenance, transportation, or personal-support expenses may increase. Federal retirement-planning resources recommend estimating both present expenses and how those expenses may change over time.
🌿 Simple Tip
Follow the rule: Needs first, priorities second, extras third.
Pay for essential housing, food, healthcare, transportation, insurance, and required debt payments before committing money to optional purchases. Your personal priorities—such as travel, hobbies, gifts, or helping family—can then be included within what remains.
Plan for Taxes and Retirement Withdrawals
Retirement income is not always tax-free. Depending on your circumstances, taxes may apply to:
• Pension and annuity payments
• Traditional IRA withdrawals
• 401(k) and similar retirement-plan distributions
• Investment earnings
• Rental income
• Part-time or self-employment income
• A portion of Social Security benefits
Traditional retirement-account withdrawals are generally included in taxable income except for amounts that were previously taxed. Roth-account rules are different, and qualified Roth distributions may be tax-free.
Some retirement accounts are subject to required minimum distributions, commonly called RMDs. Under current law, the starting age is generally 73 for people born from 1951 through 1959 and 75 for people born in 1960 or later; people born earlier may have started under previous rules. Roth IRAs and designated Roth accounts in 401(k) and 403(b) plans generally do not require RMDs during the original owner’s lifetime. Workplace-plan exceptions may apply, so verify the current IRS rules or consult a qualified tax professional.
When planning withdrawals, consider:
• How much you need for current expenses
• How long the savings may need to last
• The tax effect of the withdrawal
• Whether the withdrawal could affect Medicare-related costs
• Whether selling investments during a market decline can be avoided
• How much should remain available for emergencies
💡 Remember: Some taxable retirement withdrawals can increase your modified adjusted gross income (MAGI). Higher income can increase Medicare Part B and Part D premiums through the income-related monthly adjustment amount (IRMAA). Social Security generally uses tax-return information from two years earlier when determining these income-related premiums.
Avoid making a large retirement-account withdrawal based only on the account balance. Consider the possible taxes and the effect on future income first.
Build an Emergency Reserve
Unexpected expenses do not stop after retirement. Emergencies may include:
• Home or appliance repairs
• Vehicle repairs
• Medical or dental bills
• Travel for a family emergency
• Pet care
• A sudden increase in insurance or utility costs
• Temporary loss of part-time or rental income
There is no single emergency-fund amount that is right for everyone. Your goal may depend on your monthly expenses, health, housing, insurance coverage, access to credit, family support, and reliability of income.
Some people work toward several months of essential expenses, while others begin with a smaller goal. The CFPB advises that the appropriate amount depends on the individual’s situation and notes that even a modest reserve can provide some protection from financial shocks.
Keep emergency money somewhere that is:
• Safe
• Easily accessible
• Separate from everyday spending
• Not exposed to significant investment loss
After using emergency savings, rebuild the fund gradually when possible.
Manage Debt Carefully
Debt payments can place additional pressure on a retirement budget, particularly when income is fixed or limited.
Make a list of each debt, including:
• Current balance
• Interest rate
• Minimum monthly payment
• Remaining repayment period
• Whether the interest rate can change
• Whether the debt is secured by your home or another asset
Continue making at least the required minimum payments. High-interest debt may deserve priority, but do not automatically drain emergency savings or make a taxable retirement withdrawal to pay it off. Compare the interest saved with possible taxes, penalties, lost investment income, and the need to maintain accessible savings.
Try to avoid using credit for routine living expenses unless you have a clear repayment plan. If you are struggling:
• Contact the lender before missing payments.
• Ask whether hardship or modified-payment options are available.
• Review the budget for expenses that can be reduced temporarily.
• Consider speaking with a reputable nonprofit credit counselor.
Nonprofit credit counselors can help consumers review debts, create budgets, and consider debt-management plans. Debt-settlement companies are different and may charge substantial fees or encourage actions that worsen the debt.
Protect Yourself From Financial Scams
Scammers target people of all ages, but retirees may have accumulated savings, home equity, or dependable benefit income that criminals try to steal.
Be suspicious when someone:
• Pressures you to act immediately
• Tells you to keep the situation secret
• Claims your Social Security number or bank account is in danger
• Tells you to move money to “protect” it
• Asks for gift cards, cryptocurrency, cash, or wire transfers
• Requests remote access to your computer
• Claims to be from Medicare, Social Security, the IRS, a bank, or a technology company
• Instructs you not to contact your bank or family
• Uses threats of arrest, account closure, or loss of benefits
Government agencies do not demand payment through gift cards, wire transfers, cryptocurrency, or payment apps. The FTC advises people to stop, hang up, and contact the organization independently using contact information they know is genuine.
Never rely solely on caller identification because it can be falsified. Before sending money, talk with a trusted person who is not involved in the transaction.
Review Your Insurance and Medicare Coverage
Insurance needs can change during retirement. Review your coverage periodically and after major changes involving your health, home, vehicle, marriage, finances, or family responsibilities.
Coverage to review may include:
• Medicare
• Medicare Advantage or Part D drug coverage
• Medigap coverage
• Employer or retiree health insurance
• Homeowners or renters insurance
• Automobile insurance
• Life insurance
• Long-term care insurance, when applicable
Medicare Advantage and Part D plan coverage, provider networks, drug formularies, premiums, and cost-sharing can change. If you are enrolled in one of these plans, review its Evidence of Coverage each year to determine whether it will continue to meet your needs.
Do not choose a plan based only on its monthly premium. Consider:
• Deductibles
• Copayments and coinsurance
• Prescription coverage
• Provider and pharmacy networks
• Out-of-pocket limits
• Travel coverage
• Extra dental, hearing, or vision benefits
• Prior-authorization requirements
Free, personalized Medicare counseling is available through the State Health Insurance Assistance Program, commonly known as SHIP. SHIP counselors are not connected to an insurance company or health plan.
Prepare for Healthcare and Long-Term Care Costs
Healthcare expenses may include much more than insurance premiums.
Plan for possible costs involving:
• Premiums
• Deductibles
• Copayments and coinsurance
• Prescription medications
• Dental treatment
• Routine vision care and eyeglasses
• Hearing aids
• Medical equipment
• Transportation to appointments
• Home assistance
• Rehabilitation
• Long-term services and support
Original Medicare generally does not cover routine dental care, routine eye examinations for glasses, hearing aids, or most long-term custodial care. Some Medicare Advantage plans offer additional dental, hearing, or vision benefits, but the benefits and limitations vary by plan.
Long-term care may include help with bathing, dressing, eating, transportation, meals, or other everyday needs. Medicare generally does not pay for this type of ongoing custodial care. Medicaid may help eligible individuals, and private long-term care insurance is another possibility, but eligibility, coverage, costs, and rules vary.
Planning does not necessarily mean purchasing insurance. It means understanding:
• What your current coverage pays
• What it does not pay
• What savings or income may be available
• Whether family help is realistic
• What local or government programs may be available
• Where you would prefer to receive assistance
Keep Beneficiaries and Important Documents Current
Review the beneficiary designations on:
• Retirement accounts
• Life insurance policies
• Annuities
• Transfer-on-death accounts
• Payable-on-death bank accounts
Beneficiary designations can determine who receives an account, so review them after a marriage, divorce, death, birth, or another major family change and update them when appropriate. Some employer retirement plans require a spouse’s written consent before another beneficiary can be named.
Also consider keeping the following organized:
• Will or trust documents
• Financial power of attorney
• Healthcare instructions
• Insurance policies
• Pension information
• Retirement-account statements
• Tax records
• Property and loan documents
• A list of regular bills and financial institutions
• Contact information for trusted professionals
Store sensitive information securely. Tell a trusted person where important documents can be found without casually sharing passwords, account numbers, or other private information.
An estate-planning attorney can explain which documents are appropriate under your state’s laws.
Know When to Seek Professional Help
Professional guidance may be useful when you:
• Have several retirement or investment accounts
• Need help determining how much to withdraw
• Are approaching required minimum distributions
• Are deciding between pension-payment options
• Expect a large tax bill
• Are considering an annuity, rollover, or major investment
• Have significant debt
• Are planning for long-term care
• Need a will, trust, or power of attorney
• Are managing money after the death or incapacity of a spouse
• Feel pressured to purchase a financial product
Different professionals serve different purposes:
• A financial planner or investment adviser may help with investments and withdrawal planning.
• A qualified tax professional may help with tax planning and returns.
• An estate-planning attorney may prepare legal documents.
• A nonprofit credit counselor may help with budgeting and debt.
• A SHIP counselor may help compare Medicare choices.
Before hiring an investment professional, ask:
• What services will you provide?
• How are you paid?
• What fees and other costs will I pay?
• Do you receive commissions or incentives?
• What conflicts of interest do you have?
• Will you act as a fiduciary throughout our relationship?
• Do you have any disciplinary history?
• Can I review your Form CRS or Form ADV, if applicable?
Investor.gov recommends reviewing services, fees, compensation, conflicts of interest, and legal or disciplinary history before choosing a broker or investment adviser.
Annual Retirement Money Checklist
At least once a year, ask:
• Do I know my current monthly income after deductions?
• Have any benefits or pension payments changed?
• Does my budget include occasional and annual expenses?
• Am I setting aside money for home, vehicle, and healthcare costs?
• Is my emergency reserve adequate for my circumstances?
• Have my debts or interest rates changed?
• Do I understand the tax effect of retirement withdrawals?
• Do I have any required retirement-account distributions?
• Have I reviewed my Medicare or other insurance coverage?
• Are my beneficiaries current?
• Are my important financial and legal documents organized?
• Have I checked my financial accounts for suspicious activity?
• Does a trusted person know where essential information is stored?
A yearly review cannot prevent every unexpected expense, but it can reveal problems before they become more difficult to manage.

🌿 Golden Moment
Financial peace of mind does not come from having everything—it comes from making thoughtful choices with what you have.
Each bill you organize, expense you plan for, and question you ask is a step toward greater confidence. A simple plan today can help you enjoy retirement with more security, freedom, and peace of mind.
Related Articles
Looking for more information about retirement planning, benefits, and financial well-being?
These articles may help:
• Understanding Social Security Benefits: What Every Retiree Should Know
Learn how retirement benefits are calculated, when you may begin receiving them, and what factors can affect the amount you receive.
• Understanding Medicare: A Beginner’s Guide
Explore the basic parts of Medicare, common coverage choices, important enrollment periods, and possible out-of-pocket costs.
• Understanding Medicaid: A Beginner’s Guide
Learn how Medicaid helps eligible individuals receive healthcare and long-term support, why benefits vary by state, and where to apply for assistance.
• Preventing Senior Scams and Fraud: How to Stay Safe
Recognize common warning signs, protect your personal and financial information, and learn what to do when a call, message, or request seems suspicious.
📚 Sources & Further Reading
• Consumer Financial Protection Bureau: Planning for Retirement
• Consumer Financial Protection Bureau: An Essential Guide to Building an Emergency Fund
• U.S. Department of Labor: Retirement Toolkit
• Internal Revenue Service: Retirement Plan and IRA Required Minimum Distributions
• Internal Revenue Service: Tax Information for Seniors and Retirees
• Social Security Administration: Plan for Retirement
• Medicare: What’s Not Covered?
• Medicare: Long-Term Care Coverage
• Federal Trade Commission: How To Avoid a Government Impersonation Scam
• Investor.gov: Working With an Investment Professional
• Social Security Administration: Deductions From Social Security Benefits
• Consumer Financial Protection Bureau: The Difference Between Credit Counseling and Debt Settlement
• Medicare: Evidence of Coverage
• Medicare: Get Help With Your Rights and Protections